
Thank you for Subscribing to Insurance Business Review Weekly Brief

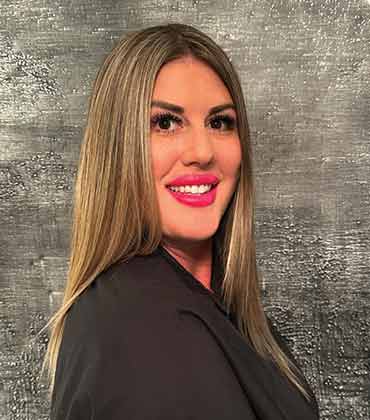 Elizabeth Cruz, CEO
Insurance requirements grow as life and business circumstances change. An auto customer may eventually become a homeowner, start a business or acquire additional assets that require new protection. That progression creates a need for an insurance partner capable of providing broader coverage as circumstances evolve.
Insurance Direct is expanding to become a one-stop insurance partner that can keep pace with evolving customer needs.
For more than 16 years, nonstandard auto insurance has been at the heart of its business. Its offering now includes both standard and nonstandard auto coverage, along with homeowners and commercial insurance. This growth is powered by the personalized service that has defined Insurance Direct’s customer relationships from day one.
“We want to become a trusted insurance resource for customers’ auto, home and business needs,” says Elizabeth Cruz, owner and CEO.
The wider offering is backed by a significantly larger carrier network. Insurance Direct represents approximately 50 auto insurance companies across Florida and Texas, along with another 15 to 20 homeowners and commercial insurance carriers. It has also expanded into Georgia. Representing multiple carriers allows the agency to serve a wider range of customer profiles, including those with different credit histories, driving records and coverage needs.
Faster Quotes, Better Coverage Decisions
The broader carrier network gives clients more options to choose from. When a customer submits a request for an insurance quote, the agency’s automation system processes the information within a few minutes and triggers follow-up communication through text messages, emails and phone calls. For auto insurance, the comparative rater uses the information provided to generate preliminary quotes from available carriers.
Technology, however, remains a support system rather than a substitute for the people. Trained and knowledgeable agents follow up with the customer to review the options, discuss coverage and understand any circumstances that may affect the policy. Once the customer is ready to move forward, the agency verifies the quote by running the customer’s driving record.
The team does not stop at the first competitive option. Because pricing can vary significantly by risk type, location and other factors, the agents may run seven or eight quotes across different carriers before recommending a policy. The process gives customers a better sense of where the strongest combination of price and coverage lies.
Homeowners and commercial insurance follow a more manual process. Not all carriers are available through comparative rating platforms, so agents have to handle more of the quoting work themselves. Even so, customers receive quotes by the end of the business day.
Responsive service continues after a policy is issued. Customers do not have to wait for the agent who originally handled their policy to become available when they need assistance. Any licensed agent can step in. A dedicated servicing team also handles service calls, with the goal of resolving requests on the initial call and avoiding unnecessary callbacks. When a carrier's pricing or requirements change, the agency reviews alternatives rather than leaving the customer to resolve the issue alone.
-
We want to become a trusted insurance resource for customers’ auto, home and business needs.
The relationship continues even when a customer is not ready to move forward. A CRM system helps agents track prospects and schedule appointments. If a customer misses an appointment, the team follows up rather than leaving the next step to the customer. Extended hours—from 9 a.m. to 7 p.m. Eastern on weekdays and 10 a.m. to 3 p.m. Eastern on Saturdays—give customers more flexibility to reconnect when they are ready.
A Broader Vision for Insurance Growth
Continued investment in technology and business systems supports a growing customer base while keeping hold times to one or two minutes, whenever possible.
Artificial intelligence also supports the team’s day-to-day work. The system transcribes customer calls, generates summaries and posts the information to the customer’s profile, reducing the time agents spend documenting conversations and making previous interactions easier to review. Customers can also use forms on the agency’s website to request policy changes or ask billing questions without calling. The servicing team receives those requests and follows up when additional information or payment is needed to complete the request.
The next phase of growth is centered on expanding the homeowners and commercial book of business and building further into the standard market while continuing to serve its established nonstandard auto customers.
For Insurance Direct, that means expanding its reach without compromising the responsive, accessible service customers have come to expect.
Car Insurance Selection Built Around Market Choice
Car insurance procurement becomes difficult when price pressure collides with uneven underwriting. A driver who looked inexpensive to insure at the last renewal can move into a different risk band after a ticket or carrier repricing. For executives arranging coverage, the useful question is not which insurer advertises the lowest rate. It is whether the agency can search enough of the market to find a workable fit without weakening protection simply to reduce premiums. That distinction matters when coverage is being purchased for people whose histories do not fit one underwriting profile or whose assets make minimum limits an inadequate benchmark.
Carrier access matters because underwriting appetite varies sharply. One insurer may favor a clean driving record, while another prices a complicated history more competitively. A narrow panel can leave buyers comparing only a small slice of the market. Broad access is more useful when paired with disciplined quote comparison, since rates can shift by driver profile and location. The agency should also be able to explain why one policy fits better than another instead of reducing the decision to a monthly payment. More carrier relationships can preserve options when a renewal becomes unattractive, allowing the agency to re-shop coverage rather than leaving the customer to restart the process elsewhere.
Speed deserves similar scrutiny. Fast quoting is useful only when the information behind the quote is checked before coverage is bound. Buyers should look for a process that moves quickly at the start but still leaves room for a licensed agent to review coverage limits and driving history. Service access after purchase matters just as much. Carrier rate changes or document problems can create friction long after the original sale. The real test is whether the agency can respond at the point of need instead of turning every change into a callback queue.
[QUOTE1_Replace]
Effective service models reduce that friction through shared account access and consistent follow-up. A customer should not be forced to wait for the one agent who handled the original quote. Timely response becomes especially important when a policy change has billing consequences or when a carrier decision requires another market check. Digital request forms can help with routine servicing, but they work best when a trained person remains available for issues that require judgment. Extended service hours can add practical value for customers who cannot deal with insurance matters during a standard workday.
A-1 Insurance Direct fits this buying logic through a brokerage model that spans standard and nonstandard auto coverage. Its agents use automated quoting support across a broad carrier panel, and then review coverage with customers before a policy is finalized. The agency separates servicing from sales, allowing another trained agent to step in when the original contact is unavailable. Online quote and service requests add another access point for customers who cannot call during business hours. For buyers who place weight on broad market comparison, responsive servicing and licensed-agent involvement, A-1 Insurance Direct merits consideration as a practical car insurance provider.
...Read more
Car Insurance Services Info
Q1
What Do Car Insurance Services Typically Include?
Car Insurance Services assist drivers in obtaining coverages that are suitable according to their individual circumstances, budget, and requirements for protection. These services may involve comparing quotes, choosing a policy, making changes to the coverage, obtaining discounts, selecting deductibles, and offering continued support with the policy. Good Car Insurance Services also help make the process easier to understand, especially in cases where a driver's record, coverage history, or financial position makes it difficult to get standard options. Insurance Direct concentrates on this personal approach by comparing deals from various insurers in order to find appropriate coverage and providing quotes by phone.
Q2
How Does Insurance Direct Approach Car Insurance Services?
Insurance Direct has designed its system with accessibility and personal assistance in mind. Its agents are able to compare policies offered by various insurers, give quotes over the phone, and arrange a policy in about 30 minutes' time. The company also deals specifically with non-standard auto insurance in Florida, Texas, and Tennessee, helping customers who have trouble getting standard coverage.
Q3
How Can Car Insurance Services Help Manage Premium Costs?
Car Insurance Services will assist customers in looking at the various factors that influence their premiums rather than just taking the first quoted price. In different situations, this could mean checking the deductibles, spotting any discounts to which they are entitled, cancelling any optional cover that is not needed, or thinking about how future improvements to their driving record might impact the price. The aim is to achieve a balance between affordability and adequate protection instead of lowering the premium at the cost of useful coverage.
Q4
What Should Customers Consider When Comparing Car Insurance Services?
A good example of comparison should not be limited to the headline premium. When assessing a policy, customers must take into account the extent of the coverage, the deductibles, the exclusions, the available discounts, the policy conditions, and the quality of the assistance offered when information has to be updated or a claim is made. It is also important for Car Insurance Services to ensure that the policies they offer are easy to understand. Clear communication is important since a cheaper price does not always mean that it is the better option if it results in important risks being inadequately covered.
Q5
How Do Car Insurance Services Support Drivers With Non-Standard Needs?
People who are non-standard drivers might find it more difficult to secure cheap insurance due to things like their driving record or breaks in their prior coverage. Car Insurance Services overcomes this problem by comparing the different underwriting options and spotting policies that suit the driver's particular situation. Although Insurance Direct deals specifically with non-standard motor insurance in Florida, Texas, and Tennessee, its agents evaluate each customer's individual case rather than using the same method for all customers.
Q6
Why Is Personalized Assistance Important in Car Insurance Services?
Personalized assistance enables customers to reach better insurance decisions whenever their requirements differ or when they need help in understanding their options. Insurance Direct teaches its agents to show empathy and clarity when taking calls, to establish trust swiftly, and to efficiently deal with routine requests. With regard to its Car Insurance Services, the company provides customers with direct support rather than asking them to look after each step themselves through automated systems.
