
Thank you for Subscribing to Insurance Business Review Weekly Brief

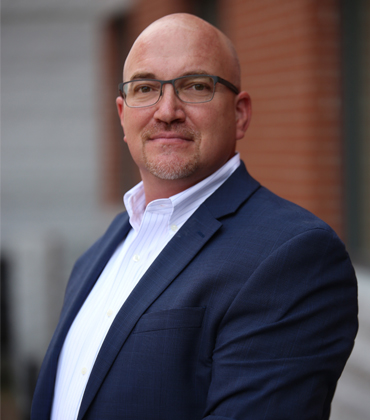 Mike DeLuca, Managing Partner
Accounts receivable can represent one of the largest assets on a company’s balance sheet, yet they are also the only major asset controlled entirely by someone else. Because businesses cannot make customers pay, receivables require deliberate management to prevent loss.
One Source Risk Management approaches credit risk with the same attention businesses give other material risks, treating receivables as an asset warranting active management.
A division of Alliant Insurance Services, Inc., One Source helps clients assess and protect receivables through credit insurance solutions built around how each business operates. Its work spans coverage, credit information and risk management, giving clients support across the broader credit function.
“We’re a service company first and a sales company second. Our client-focused approach allows us to do things others can’t,” says Mike DeLuca, managing partner.
That philosophy reflects the nature of trade credit itself. Unlike a commodity insurance product, it requires ongoing service as customers, markets and transactions change. One Source’s specialists stay close to those changes, bringing industry knowledge and tailored expertise to clients.
Customizing Protection around Real Exposure
One Source’s industry teams bring expertise across energy, food and technology. In energy, for example, its team includes former traders, risk managers and risk bankers with industry expertise. That firsthand experience helps understand the factors shaping each client’s credit exposure.
It evaluates the client’s industry, geography, variable gross margins and receivables turns, then weighs those against risk tolerance and financial objectives. For instance, if accounts receivable are pledged to a bank, the available advance rate becomes part of the calculation. Insured receivables can also strengthen the borrowing base, potentially improving advance rates and funding economics. It can then use credit insurance as part of a broader financial strategy, with the policy designed around goals like improving profits and lowering days sales outstanding.
-
We’re a service company first and a sales company second. Our client-focused approach allows us to do things others can’t.
One Source’s scale gives it leverage with carriers, helping turn client-specific analysis into tailored coverage. The team determines the right solution first, using customized policies and endorsements where needed, before addressing the economics.
Its service team supports this process, staying close to changing credit needs rather than treating coverage as a one-time transaction. A dedicated client information services team gathers financial, banking and trade information to help establish or re-establish limits that carriers have declined, reduced or removed. In a single year, its team put more than 89 million dollars of previously declined, reduced or removed coverage back on policies.
Where necessary, it also builds a risk structure around an individual debtor to get coverage back in place. For customers entering new markets, the company also assesses factors like political risk, country grades, import and export licenses and the incoterms governing a transaction.
Moving Beyond a Single Credit Solution
Credit insurance is only one part of One Source’s broader credit support. Rather than treating trade credit as another insurance product, it combines credit information, monitoring and technology to support the broader finance and credit function. This includes Compass, a credit management platform designed to fill gaps in the credit function when clients lack the staff or budget to handle them internally.
For businesses facing tighter lending and higher funding costs, structured credit offers another way to approach liquidity. One Source has a dedicated team focused on these transactions, including off-balance-sheet solutions that can provide liquidity without adding traditional debt to the balance sheet.
As AI accelerates the speed at which credit decisions need to be made, One Source sees technology becoming an increasingly important part of the credit function while human judgment remains essential.
For One Source, these capabilities ultimately come back to the same asset— receivables exposed to decisions outside a company’s control. Rather than treating credit insurance as a standalone product, it positions coverage as part of a broader financial strategy built around each client’s risk, liquidity and growth objectives.
Credit Insurance Built Around the Business
Accounts receivable can sit among a company’s largest assets while remaining unusually exposed to decisions made outside the business. Customers determine when, and sometimes whether, invoices are paid. For finance leaders, credit insurance therefore deserves scrutiny beyond premium cost. The brokerage decision affects how much receivable risk can be transferred and how confidently a company can extend credit without creating an exposure it cannot absorb.
Price-led comparisons can obscure the harder question of policy fit. Gross margin and receivable turns influence how much loss a company can tolerate before a sale stops being profitable. Lending arrangements matter too, particularly when receivables are pledged to a bank or borrowing availability depends on eligible assets. A broker should be able to translate the sales model and risk tolerance into coverage that supports growth while keeping the cost discussion in its proper place.
Financing consequences belong in the same discussion. Insured receivables can influence how lenders assess collateral quality, borrowing costs, advance rates and the eligible borrowing base. A broker that understands insurance and lending mechanics can help buyers judge whether a proposed structure protects against nonpayment while also supporting access to working capital.
“One Source Risk Management’s Client Information Services team gathers financial and banking data to pursue buyer limits that carriers have declined or reduced, while debtor-specific structures can address harder cases.”
Industry knowledge changes the quality of that design. A policy built for an energy company may require different questions and endorsements than one created for a food distributor. Geography adds another layer. International sales can bring political risk, country grades, import and export licensing and Incoterms into the credit decision. Market access alone does little if the broker cannot interpret how those conditions affect buyer limits and policy structure.
Service after placement is equally revealing. Buyer limits can be declined or reduced as customer conditions change, leaving a company with sales opportunities that no longer fit comfortably inside its risk tolerance. Restoring usable coverage often depends on obtaining financial and banking information that a carrier does not already have. A broker should be prepared to gather that material and challenge a coverage decision. Harder cases may also require a structure designed around a particular debtor rather than a standard policy response.
Credit departments also carry work that sits outside the policy itself. Credit reports, country reports, receivables support and software tools can improve the information available before a sale is approved. Access to those resources matters when internal teams lack the staff or budget to handle every credit task themselves. Buyers should look closely at whether a broker can stay involved across the credit function instead of disappearing once the policy is bound.
One Source Risk Management is a premier choice for buyers who want credit insurance treated as a finance tool rather than a commodity purchase. It designs programs around industry economics, geography, client risk tolerance and lending arrangements, then uses sector specialists to shape coverage around the business itself. Its Client Information Services team gathers financial and banking data to pursue buyer limits that carriers have declined or reduced, while debtor-specific structures can address harder cases.
One Source also supports the credit function through receivables management, credit information, software tools and broader credit support. That combination makes the firm most relevant to executives who value customized policy design and hands-on service after placement, not simply access to a lower quoted premium.
...Read more
Company : One Source Risk Management (Division of Alliant Insurance Services, Inc.)
ManagementMike DeLuca, Managing Partner
