
Thank you for Subscribing to Insurance Business Review Weekly Brief

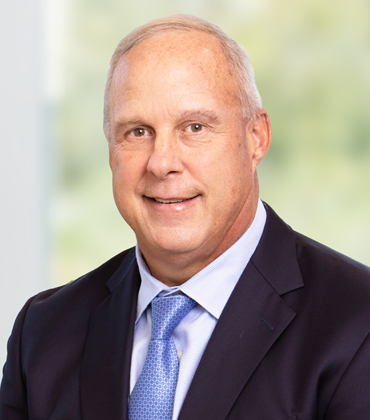 Rick Kahlbaugh, Chairman & CEO
In a market where risks continue to evolve faster than traditional insurance models can respond, The Fortegra Group, Inc. has built its reputation around helping partners navigate complexity.
As a global specialty insurer and part of DB Insurance Co., Ltd., Fortegra works primarily with managing general agents and distribution partners that need more than insurance capacity. They seek underwriting expertise, speed to market, program flexibility, operational support, and financial stability.
Fortegra’s approach combines technology and data-driven insights to help partners understand changing exposures and make informed decisions about complex risk. The company analyzes data to identify emerging trends, pricing opportunities, and risk concentrations while connecting underwriting, claims, and actuarial insights into a feedback process. This approach allows partners to respond earlier when conditions shift and strengthen the performance of their programs.
A Partner Focused Specialty Model
Fortegra serves diverse markets across a range of distribution models, including MGAs, financial institutions, auto dealers, manufacturers, medical device companies, and individual risk placements for certain classes Rather than applying a standard approach, the company develops tailored solutions based on the unique economics, customer relationships, and risk profiles of each market.
Fortegra bring together underwriting, actuarial, claims, compliance, technology, and product expertise to create programs aligned with partner goals. Whether supporting a specialized casualty portfolio, an embedded protection product, or a risk-transfer structure, Fortegra focuses on understanding the exposure and building sustainable solutions.
“Our partners bring us the risks that don’t fit neatly anywhere else,” says Rick Kahlbaugh, Chairman & CEO, The Fortegra Group, Inc. “We earn that trust by understanding the exposure, underwriting it with discipline, and building programs that still perform years from now.”
Strength through Expertise and Technology
Specialty insurance requires the ability to evaluate emerging risks with discipline and flexibility. Fortegra’s underwriting philosophy is built around maintaining strong risk selection while remaining open to innovative coverage solutions. The company supports complex opportunities, from evolving cyber exposures and catastrophe-sensitive property risks to highly specialized commercial needs.
-
Our partners bring us the risks that don’t fit neatly anywhere else. We earn that trust by understanding the exposure, underwriting it with discipline, and building programs that still perform years from now.
Technology plays an important role in improving underwriting decisions. Fortegra uses data science and automation to identify patterns, evaluate portfolio performance, and support underwriters with insights into programs. The company views technology as a tool that enhances human judgment rather than replacing the expertise required to assess complicated risks.
Claims are where a carrier’s promises get tested. Through early intervention, proactive containment, and specialized support for complex losses, the company works to improve outcomes for policyholders and partners. Claims insights also feed back into underwriting and portfolio management, creating a cycle of continuous improvement.
Global Reach, Local Understanding
Operating across the Americas, Europe, the UK, and Asia, Fortegra combines global resources with local market knowledge. The company’s international platform is supported by experienced teams who understand regional regulations, distribution practices, and customer expectations. This balance enables partners to access capabilities while maintaining responsive relationships.
Fortegra’s acquisition by DB Insurance, which closed on May 29, 2026, marked a defining step for the company. The partnership brings together Fortegra’s specialty insurance capabilities with DB Insurance’s financial strength and global ambitions. Following the acquisition, Fortegra’s insurance subsidiaries received upgraded financial strength ratings, reinforcing confidence among its partners.
Looking Ahead
As the specialty insurance landscape continues to change, Fortegra remains focused on disciplined growth, strong distribution partnerships, and investment in expertise and technology. “The carriers that who win the next decade will understand complex risk better than anyone and show up for their partners every time,” Kahlbaugh says.
Recognized for its commitment to advancing specialty insurance and risk management capabilities, The Fortegra Group, Inc. has been named Top Specialty Insurance and Risk Management Solutions 2026.
With a foundation built on underwriting discipline, innovation, and collaboration, Fortegra continues to support partners seeking a carrier equipped to address today’s challenges and tomorrow’s opportunities.
When Specialty Risk Outgrows Standard Insurance
Specialty insurance is hardest to assess when the exposure does not fit cleanly inside established forms, pricing history or standard classifications. Buyers are often comparing more than capacity. They are weighing how quickly a carrier can understand an unfamiliar risk and how much underwriting judgment sits behind the quote, while also judging whether the relationship can support a program after launch and through changing conditions. A provider that can write unusual business but cannot monitor changing conditions leaves the buyer carrying uncertainty that may surface later through pricing shifts, claims friction or reduced appetite.
Underwriting discipline therefore deserves close attention. Flexibility matters in specialty markets, particularly where rate and form can be adapted to emerging exposures, but flexibility without clear appetite can create unstable programs. Buyers should examine how a carrier evaluates unfamiliar risks and tests pricing assumptions, then how it responds when loss patterns shift or exposure assumptions no longer hold. The strongest indication is not a willingness to say yes to every opportunity. It is a repeatable process for distinguishing risks that can be supported from those that should be declined or restructured.
Program monitoring is equally important because specialty exposures can change after inception. Portfolio data should inform underwriting decisions while claims experience should feed back into pricing and risk selection. Buyers benefit when these functions are connected rather than treated as separate departments with limited visibility into one another. Early signals matter most when they lead to action. A useful provider should be able to identify shifts in loss behavior and concentration, then connect those findings to pricing performance and underwriting response before the economics of the program deteriorate.
“Fortegra’s model uses data science to identify emerging trends and risk concentrations while feeding claims and actuarial information back into underwriting decisions.”
Claims handling provides another practical test of the relationship. Delays, inconsistent escalation, fragmented oversight and unclear ownership can weaken both policyholder experience and distribution confidence. Buyers should look for a claims process that can intervene early on routine losses while assigning specialized attention to complex cases. Direct oversight is especially relevant where outside administrators are involved because accountability becomes harder to trace when responsibilities are dispersed across multiple parties.
Technology should support judgment rather than substitute for it. In small-premium and SME business, processing cost can make otherwise attractive risks difficult to serve, giving automation a meaningful role. The useful question is whether technology helps surface relevant information and reduce routine processing while preserving experienced review where the exposure warrants it. Buyers should be cautious when efficiency claims are detached from underwriting quality or portfolio visibility.
Fortegra combines specialty underwriting with portfolio monitoring while linking claims oversight to technology-supported decision-making across complex programs. Its model uses data science to identify emerging trends and risk concentrations while feeding claims and actuarial information back into underwriting decisions. Complex losses can receive focused attention through its Tiger Team, while internal claims oversight can be supplemented by select third-party administrators where appropriate. Fortegra also supports flexible specialty structures, including E&S business and customized programs for distribution partners. For executives comparing specialty insurance and risk management providers, that combination offers a practical basis for evaluating Fortegra when unusual exposures and program responsiveness must be balanced against disciplined risk selection and sustained carrier support.
...Read more
Specialty Insurance and Risk Management Solutions Info
Q1
What Do Specialty Insurance and Risk Management Solutions Address?
Specialty Insurance and Risk Management Solutions help cover exposures that do not fit neatly within standard insurance forms, pricing models or classifications. They may involve unusual commercial risks, changing loss patterns or coverage needs that require more tailored underwriting. The goal is to assess the exposure carefully, set terms that reflect its risk and maintain a program that can respond as conditions change.
Q2
How Does The Fortegra Group, Inc. Approach Complex Insurance Programs?
The Fortegra Group, Inc. is a global specialty insurer and part of DB Insurance Co., Ltd. It works with managing general agents and distribution partners that may need underwriting knowledge, program flexibility, operational support and a reliable source of insurance capacity. Its approach combines underwriting, actuarial, claims, compliance, technology and product expertise to shape programs around the risk profile and economics of each market. These capabilities inform its Specialty Insurance and Risk Management Solutions for complex exposures.
Q3
Which Capabilities Matter When Risks Fall Outside Standard Coverage?
Effective Specialty Insurance and Risk Management Solutions require disciplined risk selection as well as room to structure appropriate coverage. Underwriters need to understand what drives a particular exposure, test pricing assumptions and recognize when a risk should be declined or redesigned. For evolving cyber exposures, catastrophe-sensitive property risks and specialized commercial needs, providers also need to revisit assumptions as conditions and claims patterns change. Flexibility is most useful when paired with a clear underwriting appetite and ongoing portfolio oversight.
Q4
How Can Data Improve Underwriting and Portfolio Decisions?
Data can help identify emerging trends, pricing opportunities and concentrations that may otherwise be difficult to spot. In Specialty Insurance and Risk Management Solutions, value comes from connecting those findings to decisions rather than collecting information in isolation. Portfolio performance, actuarial analysis and claims experience should inform risk selection and pricing over time. Technology can support that process by surfacing relevant patterns and reducing routine work, while experienced professionals retain responsibility for interpreting complicated exposures and making underwriting judgments.
Q5
How Does The Fortegra Group, Inc. Connect Claims With Underwriting?
The Fortegra Group, Inc. connects claims insights with underwriting and portfolio management, using data science and automation to help make decisions. Their model includes early help and special support for complex losses, with claims experience informing program reviews. Fortegra works in the Americas, Europe, the UK, and Asia, blending a global platform with local knowledge of rules and distribution. This helps their Specialty Insurance and Risk Management Solutions adjust as risks and markets change.
Q6
What Should Organizations Evaluate Before Choosing a Specialty Insurance Provider?
When comparing Specialty Insurance and Risk Management Solutions, organizations should look past the first quote. Think about how a provider handles new risks, explains coverage, tracks loss trends, and reacts when things change. Claims handling, escalation, and communication are also important, especially when several parties are involved. Ask how data is used in pricing and underwriting, if complex losses get the right attention, and how the provider balances automation with human review. The right partner should show a proven process for managing risk over time, not just a willingness to take on unusual business.
