
Thank you for Subscribing to Insurance Business Review Weekly Brief

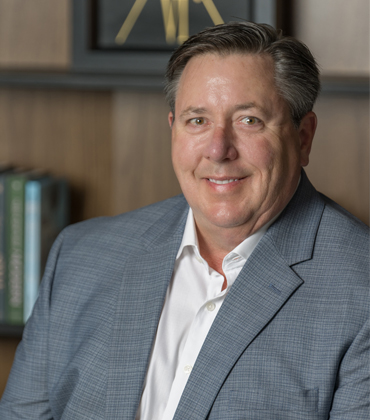 John Czapko, Founder
A company’s next move can change more than its direction. A merger, acquisition, expansion, operational change or new technology can reshape risk across the business, often long before anyone considers the insurance implications.
Thrive Insurance Group helps businesses understand how their decisions could affect their risk, giving leaders the clarity to make informed choices before they move forward. The boutique commercial insurance advisory firm looks first at the business behind the risk, understanding what the client is trying to accomplish and how the proposed change could affect it. This business-first view allows Thrive to consider risk in the context of the client’s broader goals, not simply as an insurance transaction.
Three principles guide how it works with clients: SOLVE. OWN. CLARIFY. Thrive works to understand the business problem, takes ownership of moving it toward resolution and creates clarity around the path forward. That understanding also helps Thrive advocate for the client with underwriters, presenting the business behind the risk and assessing what the market can support.
“I want Thrive to be the company that business owners call when they face a complicated business situation and need someone to drive it to resolution,” says John Czapko, founder.
Aligning Risk With Business Goals
Czapko brought an unconventional perspective to insurance. He spent 26 years in IT, working at Oracle, Microsoft, Dell and HP before helping lead a cybersecurity practice at KPMG. Coming from outside the insurance industry allowed him to question traditional approaches and build Thrive differently, starting with the business need and desired outcome rather than the insurance transaction.
That business-first thinking carries into every client conversation. Thrive looks beyond the current insurance program to understand where the business is going and what could change along the way. Acquisitions, divestitures, workforce growth, new locations, franchise expansion and changes within an industry can all reshape a company’s risk, often before the insurance implications are fully understood.
-
I want Thrive to be the company that business owners call when they face a complicated business situation and need someone to drive it to resolution.
The boutique model keeps those conversations direct, with clients working with Czapko himself as they navigate business decisions and risk. That continuity gives Thrive a deeper understanding of the business and creates an opportunity to identify the risk implications of an acquisition, expansion or new technology before the client moves forward.
Czapko’s cybersecurity background enables him to move between technical and business conversations. He can discuss cyber issues with technology leaders and connect them to risk and business priorities for CFOs and executives. That perspective allows Thrive to approach cyber as a business risk, incorporating both cyber risk quantification and cyber insurance.
Turning Risk Insight into Better Decisions
One client relationship illustrates Thrive’s role in practice. The client was growing through acquisitions, changing its franchise business model and moving into other lines of business. As the client considered an acquisition, Thrive helped evaluate the opportunity and its risk profile. After working through the implications, the client ultimately decided not to pursue the acquisition.
Thrive then identified adjacent markets that could support the client’s growth with less impact on the business. It advised the client on what to consider, why those markets made sense and how they aligned with the business from a risk perspective. The client pursued those opportunities and has continued to expand.
Specializing to Serve Better
Thrive has reached its fifth year and remains intentionally boutique, working closely with businesses where its knowledge and experience can make a meaningful difference. It continues to deepen its expertise in the specific risks and coverage needs of the businesses it serves, reflecting the growing specialization across the insurance market.
Recognition as Top Boutique Commercial Insurance Advisory Services 2027 reflects the direction Thrive Insurance Group has pursued from the start, staying close to the businesses it serves and helping them make sense of the complex risks that come with growth and change.
Commercial Insurance Advice Beyond Policy Placement
A commercial insurance renewal can proceed without difficulty even when the underlying business has changed substantially. New contracts may introduce unfamiliar liabilities, acquisitions can alter the exposure profile and expanded operations may outgrow existing coverage arrangements. The difficulty for executives is determining whether an insurance advisor understands those changes well enough to influence decisions before commitments become binding. Premium comparisons alone offer little evidence of that ability.
Boutique commercial insurance advisory services offer a more involved relationship, but the depth of involvement varies. A smaller client portfolio may allow greater attention to individual accounts without necessarily providing stronger technical judgment. Executives should establish who will examine their business, who will handle carrier discussions and whether the same advisor remains accountable when difficult coverage questions arise. Direct access to a senior professional carries particular weight when insurance decisions involve multiple business functions.
Business familiarity becomes consequential when risks extend beyond standard policy classifications. Contractors may face contractual insurance obligations that vary across projects, while manufacturers must account for changes in production methods. Franchise organizations introduce questions about how responsibilities are distributed across business entities. An advisor should understand these distinctions before recommending coverage. Industry specialization is useful when it changes the substance of the risk assessment rather than merely the terminology used in client meetings.
“Thrive Insurance Group looks beyond the insurance policy to understand the business, anticipate emerging risks and help leaders make better decisions before they move forward.”
A proposed acquisition can change liabilities before its financial benefits are realized. Opening another location may introduce exposures that existing policies were never designed to address. Insurance discussions held after these decisions leave limited room to adjust the underlying plan. Advisory relationships are more useful when they provide executives with an assessment of potential coverage consequences during planning. That requires access to business forecasts and the willingness to discuss proposed changes before an insurance transaction becomes necessary.
Cyber exposure introduces a different coordination problem. Information security executives often describe risks through system vulnerabilities and possible disruptions, while financial decision-makers examine potential losses and insurance implications. Coverage discussions can become disconnected from the technical conditions being insured. Advisors working across these perspectives should translate security exposures into understandable business consequences without reducing the discussion to policy limits. Relevant experience in technology and cyber risk can strengthen that exchange.
Underwriting outcomes also depend on how a business presents its exposure. Standard application forms capture essential information but may leave insurers without sufficient context about unusual activities or anticipated changes. Advisors who understand the business can explain those circumstances when approaching carriers. Executives should examine how an advisor prepares submissions and manages follow-up discussions. The distinction becomes particularly consequential when conventional underwriting assumptions do not adequately describe the account.
Thrive Insurance Group approaches commercial insurance through business analysis conducted before coverage recommendations. Its founder-led model gives clients direct access to the professional responsible for understanding their circumstances and engaging insurers. Thrive Insurance Group looks beyond the insurance policy to understand the business, anticipate emerging risks and help leaders make better decisions before they move forward.
Its advisory work includes assessing the insurance implications of acquisitions, location expansion and technology changes. Experience in cybersecurity also supports conversations connecting technical exposure with financial risk. The firm concentrates on complex commercial accounts, including contractors, franchises/franchisors, and professional services. This approach is particularly relevant to executives managing complicated exposures who require direct advisory involvement before major business decisions.
...Read more
Boutique Commercial Insurance Advisory Services Info
Q1
What Do Boutique Commercial Insurance Advisory Services Offer Businesses Facing Complex Risk?
Boutique Commercial Insurance Advisory Services help businesses connect insurance decisions with their broader commercial objectives. Rather than focusing solely on policy placement or renewal costs, this advisory model examines how acquisitions, expansion, contractual obligations and technology changes may affect risk exposure. The work can include evaluating coverage needs, preparing for insurer discussions and clarifying the implications of business decisions before commitments are made. This approach helps decision-makers understand potential exposures and consider insurance as part of business planning.
Q2
How Does Thrive Insurance Group Approach Commercial Insurance Advisory?
Thrive Insurance Group applies a business-first approach shaped by founder John Czapko’s 26 years in corporate leadership and information technology, including experience at Oracle, Microsoft, Dell and HP and leadership in a cybersecurity practice at KPMG. Its Boutique Commercial Insurance Advisory Services follow three principles: solve the underlying problem, take ownership of resolution and clarify the options available. The firm examines the business context behind insurance needs and advocates for clients in discussions with underwriters.
Q3
When Should a Business Seek Specialized Commercial Risk Advice?
Boutique Commercial Insurance Advisory Services can be valuable when a company is preparing for an acquisition, opening another location, expanding a franchise or changing its operations. These developments may introduce liabilities or coverage gaps that existing policies do not adequately address. Early advice gives decision-makers an opportunity to examine potential exposures before finalizing plans. It also helps connect insurance considerations with financial objectives, contractual responsibilities and operational changes rather than treating coverage as a separate administrative task.
Q4
What Should Businesses Evaluate When Choosing an Insurance Advisor?
When comparing Boutique Commercial Insurance Advisory Services, businesses should examine the advisor’s understanding of their industry, access to senior expertise and ability to manage discussions with insurers. It is also important to establish who will assess exposures, explain coverage options and remain accountable when complex issues arise. Premium comparisons alone may not reveal whether an advisor understands changing business conditions. Direct involvement and clear communication can help decision-makers evaluate trade-offs and make informed choices about coverage.
Q5
How Can Boutique Commercial Insurance Advisory Services Support Better Growth Decisions?
Boutique Commercial Insurance Advisory Services can assist executives in determining whether a suggested business relocation aligns with their long-term goals and risk tolerance. Thrive Insurance Group's work with a client growing through acquisitions and altering its franchise model serves as an example of this strategy. The firm assisted in identifying nearby markets that more closely matched the client's situation after assessing a possible acquisition and its risk profile. The client took advantage of those chances and kept growing, proving that risk analysis may influence choices other than buying insurance.
Q6
Why Do Technology and Cybersecurity Experience Matter in Commercial Insurance?
Boutique Commercial Insurance Advisory Services increasingly need to address risks that cross technical and financial boundaries. Cybersecurity concerns, for example, can involve system vulnerabilities, potential business disruption and insurance implications. An advisor who understands both technology and business priorities can help translate technical exposures into terms that financial decision-makers can assess. This perspective also supports discussions about cyber risk quantification and cyber insurance, helping organizations consider coverage alongside the underlying business consequences of technology-related risks.
